 A burst pipe, urgent dental expense, or broken refrigerator can turn an ordinary week into an expensive one. When savings are not enough, some households explore short-term financial options through Go Loan as part of a wider search for solutions. Before choosing financing, however, it is worth slowing the decision down long enough to establish what must be paid, what can wait, and what repayment would look like after the emergency is over.
Define the immediate problem
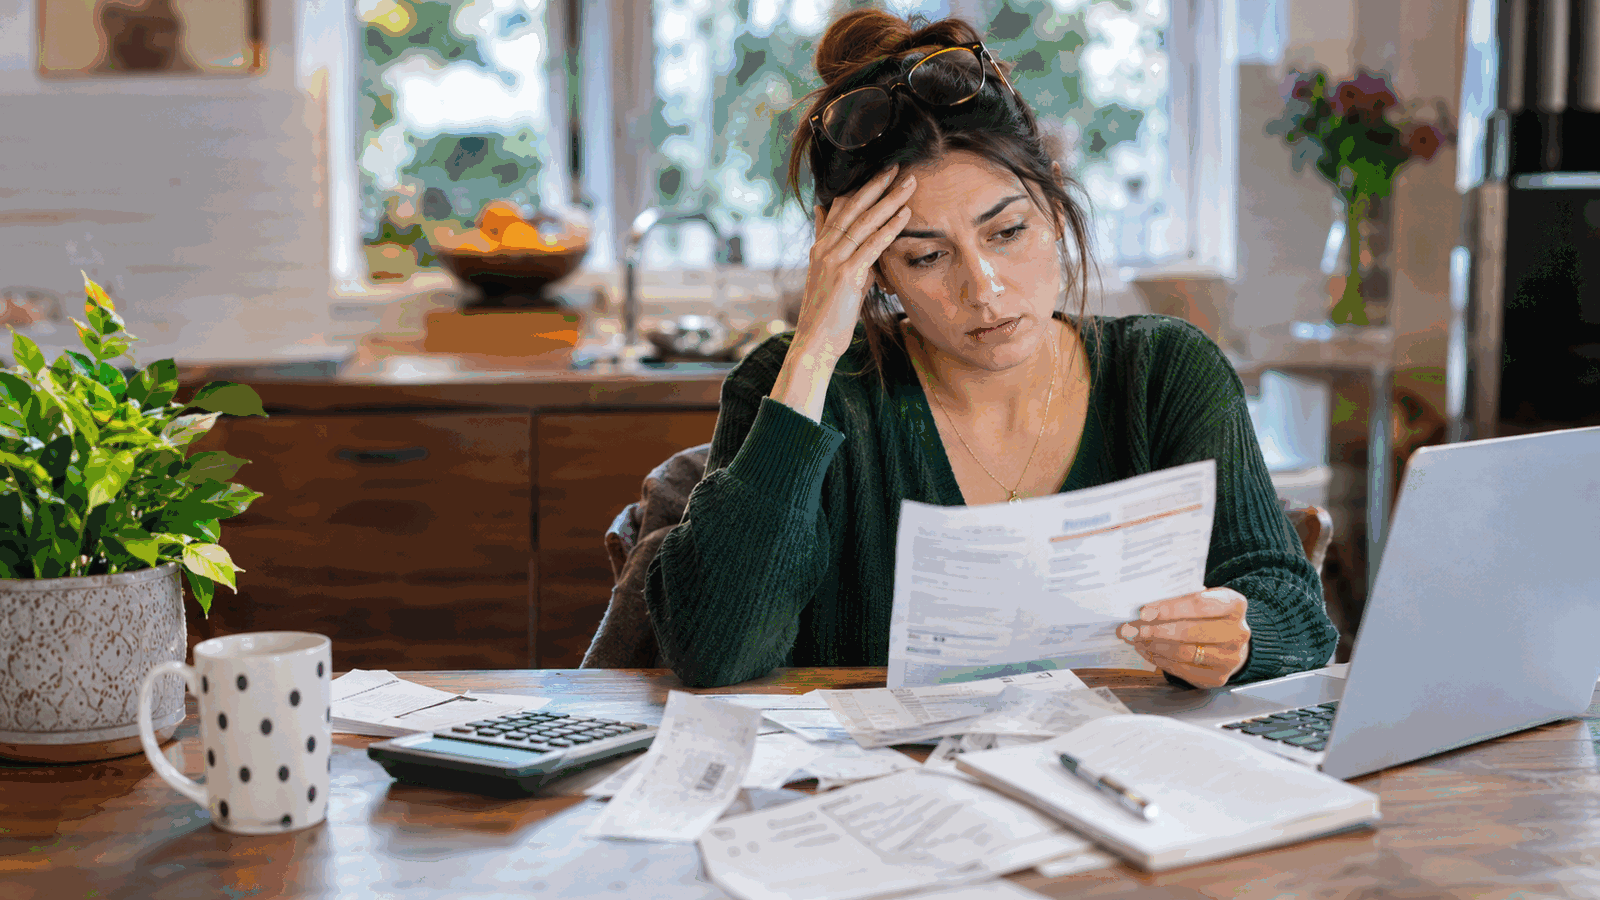
An unexpected invoice can feel like one large, urgent obligation. It may actually contain several components: an essential repair, recommended follow-up work, and optional improvements. Ask the provider for an itemized estimate and identify the minimum amount needed to restore safety or essential service.
For example, replacing a failed water-heater component may be urgent, while a broader plumbing upgrade could potentially be scheduled later. This distinction can prevent a temporary problem from turning into unnecessary long-term debt.
Look for solutions that do not add interest
Before borrowing, review what is already available. A modest emergency fund, a forthcoming reimbursement, or money set aside for a discretionary purchase may cover part of the bill. Some repair companies, health providers, and utilities may offer payment arrangements; asking costs little and can open another option.
Using every dollar of savings is not automatically ideal. A household with no cash reserve may be exposed to the next surprise. Try to preserve a basic cushion while minimizing the amount that would have to be financed.
Create a seven-day emergency spending plan
A regular monthly budget may not reveal how much money can be freed up quickly. Write down income expected in the next seven days and every essential payment due during that period. Include rent, food, transport to work, utilities, and required debt payments.
Then identify truly flexible spending. Pausing nonessential shopping or postponing entertainment can create breathing room, although these changes may not cover a large repair. Make conservative assumptions about income, especially if work hours vary. An optimistic estimate can make a repayment look safer than it really is.
If borrowing is necessary, compare the full obligation
A lender may describe a loan in terms of a payment amount or the speed of the application. Those details matter, but they are not enough. Review the full amount to be repaid, interest, permitted charges, due dates, and consequences of a missed payment.
Consider how the first payment lines up with your next paycheque. A loan that must be repaid before adequate income arrives could create a second cash shortage. Also compare the proposed financing with any lower-cost option available through your bank, credit union, or the provider sending the invoice.
Watch for pressure and misleading promises
Emergencies make people vulnerable to rushed decisions. Be wary of anyone who insists that an offer must be accepted immediately, refuses to disclose costs, or requests unusual advance payments to release loan funds. Approval should not be treated as guaranteed simply because a website accepts an online application.
Read the agreement carefully and preserve copies of all documents. If something is confusing, ask the provider to explain it in plain language before you agree.
Turn this experience into future protection
Once the immediate bill has been handled, revisit the event without treating it as a personal failure. Ask whether the expense was a rare surprise or a predictable cost that lacked a savings category. Appliances, vehicle maintenance, and seasonal utilities can often be anticipated even when the exact timing is uncertain.
A small automatic contribution to an emergency fund can gradually reduce dependence on financing. The strongest emergency plan combines practical triage today with a realistic financial cushion for tomorrow.